
Weekly Mortgage & Market Update
Will Ottawa Make It Easier to Qualify for a Mortgage?
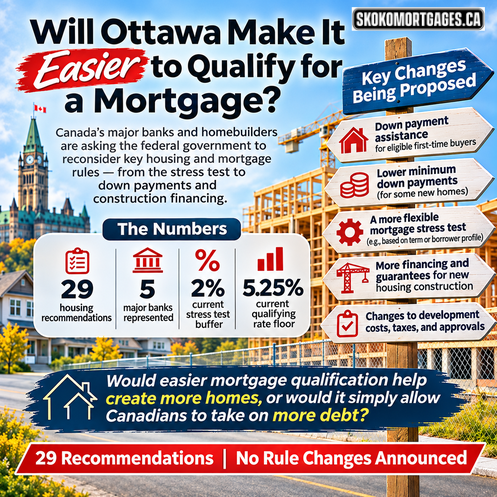
Could it soon become easier to qualify for a mortgage in Canada?
Some of the country’s largest banks and major homebuilders are asking Ottawa to reconsider several housing and mortgage rules, including the mortgage stress test, minimum down payments, construction financing, and incentives for buyers of newly built homes.
The recommendations come from the National Housing and Investment Initiative, a coalition that includes leaders from BMO, CIBC, RBC, Scotiabank, TD, and several major Canadian developers.
The group released 29 recommendations this week. Its central argument is straightforward: Canada cannot build more ownership housing if qualified buyers cannot obtain the financing needed to purchase it.
Would easier mortgage qualification help create more homes, or would it simply allow Canadians to take on more debt?
That is the question policymakers will need to answer.
What Is the Industry Asking Ottawa to Change?
The report covers much more than mortgages. It also addresses construction financing, development costs, infrastructure, immigration planning, foreign investment, and housing data.
Several proposals could directly affect homebuyers and mortgage borrowers.
- Down payment assistance for eligible first time buyers purchasing newly built homes.
- Lower minimum down payments for certain first time buyers of new construction.
- A more flexible mortgage stress test based on the mortgage term, borrower profile, or market conditions.
- Recognition of builder funded rate reductions when qualifying a purchaser.
- New financing and guarantee programs intended to help condominium and other ownership projects begin construction.
- Changes to development charges, taxes, approvals, and other costs that affect the price of building new homes.
These are industry recommendations. They are not approved government policies, and none of them changes how a borrower qualifies today.
Why the Mortgage Stress Test Is Back in the Conversation
For most uninsured mortgages at federally regulated lenders, borrowers currently qualify at the greater of the contract rate plus two percentage points or 5.25%.
For example, someone receiving a mortgage rate of 4.50% would normally need to qualify as though the rate were 6.50%.
The stress test is intended to confirm that a borrower could continue making payments if rates rise or their financial situation becomes more difficult. It also helps protect lenders and the broader financial system.
The concern raised by builders and lenders is that a single qualification buffer may not reflect every borrower or mortgage equally. A first time buyer purchasing a newly built home with a longer fixed term may present a different level of risk than someone with a shorter term, a larger debt load, or a more complex income situation.
The coalition is therefore asking Ottawa and regulators to consider more flexible qualification rules.
My Take
A more tailored qualification system may make sense if it is supported by clear evidence and responsible underwriting. But any change should be designed carefully. Increasing borrowing capacity without increasing housing supply could simply allow more buyers to compete for the same homes.
Could Minimum Down Payments Change?
The report also proposes assistance with down payments and lower minimum down payment requirements for some first time buyers purchasing newly built homes.
Reducing the amount of cash required could help buyers who have sufficient income to manage a mortgage but are struggling to save the required down payment.
However, a smaller down payment also means a larger mortgage, less initial equity, and potentially more risk if property values decline or the borrower needs to sell earlier than expected.
My Take
Down payment assistance could help a specific group of well qualified buyers, particularly if it is connected to new housing supply. It should not be viewed as a broad solution to affordability. A lower entry requirement does not reduce the purchase price or the long term cost of owning the home.
Construction Financing May Be the More Important Story
Several recommendations focus on helping viable housing projects obtain financing and move into construction.
Condominium projects often require a certain level of presales before a lender will advance construction funds. If buyers cannot qualify or sales are too slow, a project may be delayed or cancelled even when the underlying housing is needed.
The coalition proposes federal financing tools, credit guarantees, and presale support for qualifying condominium, townhome, and smaller housing developments.
It also calls for more predictable development costs and approval rules. A project that takes several years to approve can become financially unworkable if fees, financing costs, and construction expenses increase substantially during that period.
My Take
This is where policy may have the greatest long term impact. Helping responsible projects reach construction can add actual homes to the market. That addresses supply instead of only increasing the amount buyers can borrow.
What This Means for You
If You Are Planning to Buy
Do not delay a sound plan because a policy recommendation might become law later. Confirm what you qualify for under today’s rules, protect your budget, and keep appropriate financing conditions in your offer.
If You Are Buying New Construction
Review the deposit schedule, completion timeline, assignment rules, financing conditions, taxes, closing adjustments, and the risk that mortgage rates or qualification rules may be different when the home is completed.
If Your Mortgage Is Renewing
These proposals do not lower your existing mortgage payment. Start reviewing your renewal early, compare more than the interest rate, and consider how the payment fits your current cash flow and longer term plans.
Will Ottawa Actually Make These Changes?
Some recommendations are more likely to receive attention than others.
The federal government has recently shown interest in mortgage insurance changes and financing programs that support new construction. Regulators have been more cautious about weakening borrower qualification standards.
That suggests construction financing changes may move forward sooner than broad stress test or down payment relief.
It is also notable that executives from Canada’s largest banks are now publicly supporting mortgage qualification reforms. That does not guarantee action, but it adds a significant voice to the discussion.
Final Thoughts
Canada needs more homes, but it also needs those homes to be financially sustainable for the people purchasing them.
Better construction financing, faster approvals, more predictable development costs, and responsible mortgage flexibility could all contribute to a healthier housing market.
But easier access to credit should not be confused with lower housing costs.
The best policy would help build more homes while ensuring buyers can comfortably manage the debt they take on.
Until any new rules are formally announced and implemented, borrowers should continue making decisions based on the mortgage options and qualification requirements available today.
Build Your Plan Around Today’s Rules
If you are buying, renewing, or refinancing in British Columbia or Alberta, I can help you understand what you qualify for and compare the mortgage strategies currently available.
Sources
This article is provided for general educational purposes and reflects information available as of November 13, 2026. The proposals discussed are recommendations and have not been adopted as mortgage qualification rules. Mortgage rates, products, eligibility, and lender policies can change without notice and remain subject to borrower qualification, property eligibility, insurer requirements, and lender approval.
Let's talk about your goals